Rivo vs MaxMyInterest: Automated Treasury Bill Cash Management vs FDIC-Insured Deposit Optimization
Compare Rivo vs MaxMyInterest on cash type, yield source, fees, FDIC and SIPC protection, transfer timing, tax treatment, automation, and buyer fit.
Rivo vs MaxMyInterest is not a simple rate comparison. It is a product-architecture comparison between 2 different answers to the same cash problem: too much money sits idle because moving it manually is annoying, rate chasing is repetitive, and bill timing still matters.
Rivo is built for idle checking cash that should stay connected to an existing checking account and move around bills automatically. MaxMyInterest, now branded publicly as Max, is built for cash optimization across FDIC-insured high-yield bank accounts, often with higher coverage needs and advisor-friendly workflows.
If you are still comparing cash categories, start with Rivo vs High-Yield Savings vs Treasury Bills. If your problem is more basic, use What Should You Do With $20,000 Sitting in Your Checking Account? first.
TL;DR
- Choose Rivo if the core problem is idle checking cash above a safe balance, bill-aware automation, and earning through short-duration U.S. Treasury Bills while keeping your existing bank relationship.
- Choose MaxMyInterest if the core problem is FDIC-insured deposit optimization across multiple bank accounts, especially if you want expanded FDIC coverage and are comfortable with a monthly optimization workflow.
- The current Rivo rate table lists a 3.65% gross annualized rate as of July 1, 2026, before fees and taxes, and Rivo charges a 0.05% monthly management fee.
- Max's individual-investor page currently lists up to 3.57% yield on FDIC-insured cash and 16 basis points, or 0.16% per year, subject to a $20 quarterly minimum.
- Rivo uses Treasury Bills through Jiko Securities, so T-bill holdings are not FDIC-insured deposits. Max allocates cash across FDIC-insured bank accounts, so its protection model is deposit insurance rather than brokerage custody protection.
- The practical decision is not "which yield is higher today?" It is "which product structure matches the cash, protection preference, tax treatment, transfer timing, and automation job?"
Rivo vs MaxMyInterest at a Glance
The takeaway: Rivo and MaxMyInterest compete for attention from people with idle cash, but they do not package the same product. Rivo is an autopilot for checking-adjacent idle cash. Max is a deposit optimization network.
The Real Difference: Rivo vs MaxMyInterest
The real difference is cash architecture.
Rivo starts with the operating account
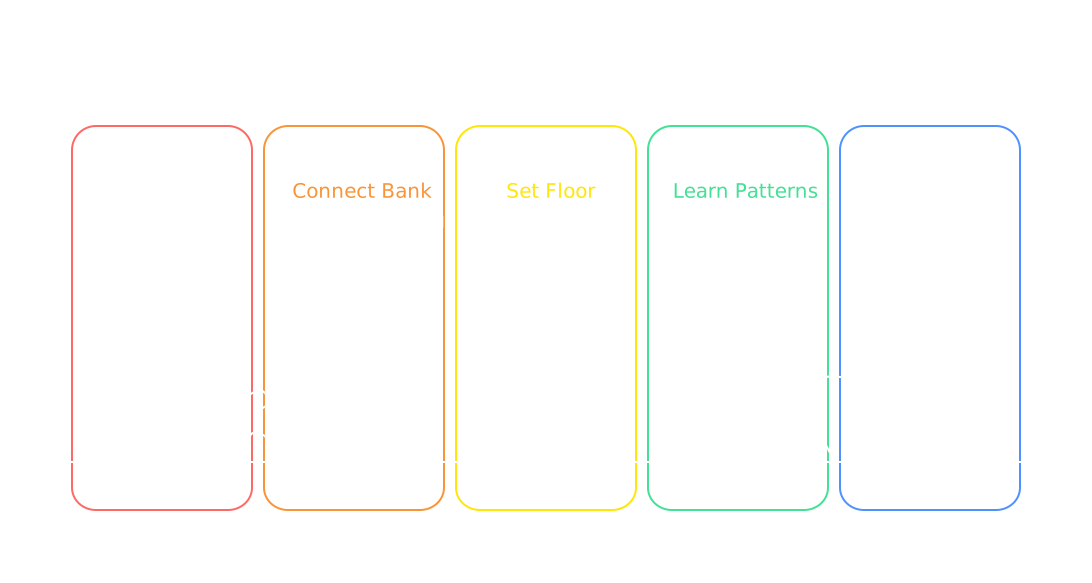
Rivo starts from your checking account. You connect your existing bank, set the amount you want to keep in checking, and Rivo identifies cash above that floor. The product flow is built around keeping your bank, linking checking, learning spending patterns, and moving money back before bills or transfers hit.
Max starts with deposit allocation
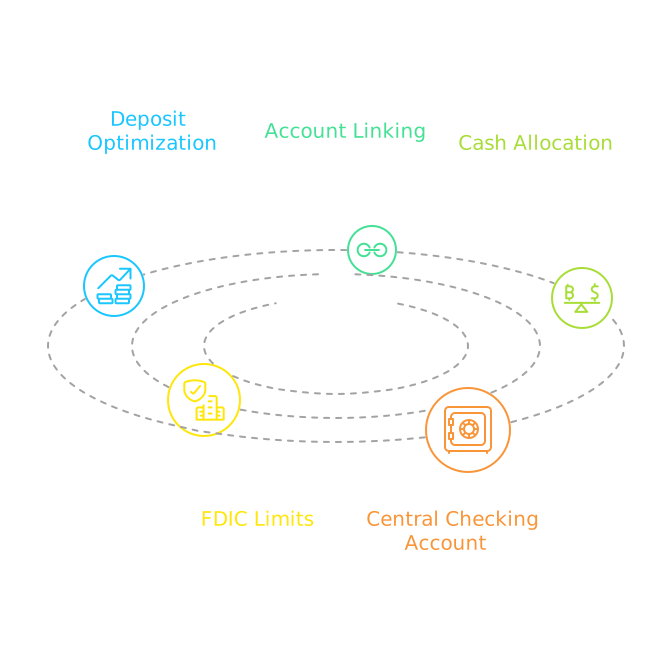
MaxMyInterest starts from deposit optimization. Max helps you open or link high-yield savings accounts at multiple banks, then allocates cash among those accounts based on rates and FDIC limits. Its individual page explains that Max helps spread cash across multiple high-yield savings accounts and uses a central checking account for optimizations.
If the cash is operational checking cash, Rivo is the more direct comparison. If the cash is already savings cash and the priority is FDIC coverage across multiple banks, Max is the more direct comparison.
Who Should Compare Rivo vs MaxMyInterest
You should compare Rivo vs MaxMyInterest if you have meaningful cash above your daily operating needs and you are tired of manually managing it.
The right buyer already knows the cash is idle
The comparison is especially relevant when the cash is not emergency cash, not investment portfolio risk capital, and not money needed for a known payment this week. It is the extra layer that stays put after bills, payroll, credit card autopay, mortgage, rent, taxes, tuition, and other recurring obligations have cleared.
This is a vendor-aware decision, but it should still start with the cash job. A product can be objectively good and still wrong for the dollars you are evaluating.
How Does Rivo Work Compared With MaxMyInterest?
Rivo works like a checking-account autopilot. Max works like a bank-deposit optimizer.
The failure mode is different
The difference matters because cash management fails in different places. For many households, the failure is not finding a better rate. It is moving cash out, remembering what needs to stay in checking, and moving cash back before bills hit. For larger deposit holders, the failure can be spreading cash across enough banks to stay within FDIC limits while still earning competitive rates.
*Movement of funds is not instant. Transfers to your linked account can take up to 3 business days to settle, and longer if a Treasury Bill must be sold first. Rivo plans around known bills. It does not guarantee same-day access or a specific arrival date.
Rivo is more directly tied to the problem in How Much Money Should You Keep in Checking?: once a safe balance is defined, the cash above that floor can be evaluated separately.
Max is more directly tied to the problem of maintaining deposit coverage and high-yield bank exposure across multiple accounts.
Fees, Side by Side
Rivo currently charges 0.05% monthly, which is about 0.60% per year before compounding. Max currently lists 16 basis points, or 0.16% per year, billed quarterly and subject to a $20 quarterly minimum.
Fee math changes by balance size
That makes Max cheaper on stated platform fee. But a fee comparison alone can mislead because the 2 tools are not doing the same job.
The decision is whether the higher Rivo fee is paying for a different kind of automation. If your cash problem is "I need FDIC-insured deposit optimization for a large savings balance," Max has the fee advantage. If your problem is "I keep too much in checking because I do not want a bill timing problem," the Rivo fee has to be judged against the value of bill-aware automation.
Rates Compared: Gross, After-Fee, and After-Tax
Current rates change, and a comparison article should not pretend otherwise. The current Rivo rate table lists a 3.65% gross annualized rate as of July 1, 2026, before fees and taxes. Max's individual-investor page lists up to 3.57% yield on FDIC-insured cash.
Compare current, after-fee, and after-tax numbers
The national interest-checking benchmark is much lower: FRED lists the national interest checking rate at 0.07000% for June 2026.
The right rate comparison is after fee, after tax, and after workflow fit. A slightly higher gross rate can be worse if the product does not match the cash job. A lower fee can be irrelevant if the product does not solve the reason the cash stayed idle.
What Would the Same $20,000 Look Like?
Use the same $20,000 example only as a sizing exercise. It is not a promise and not a projection.
Keep the example narrow
At the 0.07% national interest-checking rate, $20,000 earns about $14 per year before tax. At the current 3.65% listed Rivo rate as of July 1, 2026, $20,000 earns about $730 before fees, taxes, balance changes, and timing effects. Max's current public page lists up to 3.57%, which implies up to about $714 before its listed fee, taxes, rate changes, and balance changes.
This table shows why fee-only comparison is incomplete. On $20,000, Max's $20 quarterly minimum matters more than 0.16% fee math. The Rivo fee is higher, but it is attached to a different operating promise: automating checking surplus around bills.
If your starting balance is exactly $20,000, use the full walkthrough in What Should You Do With $20,000 Sitting in Your Checking Account?.
FDIC vs SIPC: Which Protection Model Fits Your Cash?
FDIC and SIPC are not interchangeable.
FDIC applies to deposit accounts
The FDIC explains that deposit insurance protects money in deposit accounts at FDIC-insured banks and covers at least $250,000 per depositor, per ownership category, at each FDIC-insured bank. The FDIC also lists U.S. Treasury bills, bonds, and notes under products not covered by FDIC deposit insurance.
SIPC applies to brokerage custody failures
SIPC explains that it protects customer cash and securities at a financially troubled SIPC-member brokerage firm, with a $500,000 limit including a $250,000 cash limit. SIPC protection is about missing assets in brokerage custody; it does not protect against market-value changes.
Choose Max if your requirement is FDIC-insured deposits. Choose Rivo only if you are comfortable with Treasury Bill exposure, brokerage custody protections, and the specific timing and liquidity trade-offs of a T-bill-based cash product.
For a deeper safety breakdown, read Are Treasury Bills Safe for Short-Term Cash?.
Where Tax Treatment Diverges
Tax treatment is another structural difference.
Treasury income and bank deposit income are not the same category
TreasuryDirect explains that Treasury marketable security interest is subject to federal tax and exempt from state and local income taxes. Bank deposit interest is generally reported as interest income and does not receive that Treasury-specific state and local tax treatment.
The tax question can change the after-tax result, especially in high-tax states. It should not be guessed. Use the product documents and a qualified tax advisor before making a decision.
Which Product Is Better for Bills and Safe Balance?
Rivo is the more direct fit when the core problem is checking-account safe balance.
Bill timing is a separate requirement from yield
The workflow starts by linking checking, telling Rivo how much you always want in the account, and moving money back as bills and transfers approach. Users can configure a minimum threshold and receive an email at 5PM Pacific before money moves, with time to cancel.
Monthly optimization is useful, but not identical
Max can help keep liquidity, but its core optimization frame is different. Its FAQ describes a monthly optimization that helps allocate cash among bank accounts, plus on-demand optimization and bank transfers that typically take 1-2 business days.
If the fear is "I might miss a bill," Rivo is built around that fear. If the fear is "my deposits exceed FDIC limits," Max is built around that fear.
Which Product Is Better for Larger Cash Balances?
MaxMyInterest becomes more compelling as cash balances get larger and FDIC coverage becomes the decision driver.
Large cash balances often have a coverage problem
Max documents that many members optimize between $50,000 and $5 million, and individuals can link multiple online savings accounts to obtain up to $2 million of incremental FDIC insurance, with higher coverage possibilities for joint and multiple-account structures.
Checking surplus is a narrower slice of cash
Rivo can still be relevant for larger checking balances, but only when the problem is checking-adjacent idle cash and the user wants Treasury bill automation around an operating floor.
The larger the balance, the more the FDIC coverage architecture matters. The more the cash behaves like checking surplus, the more the safe-balance automation matters.
The Trade-Offs Most Comparison Tables Miss
Most comparisons over-focus on yield and fee. The real trade-offs are operational.
Operational fit beats a single percentage point
The Rivo trade-off is that you pay a higher management fee for a system that is focused on checking surplus, safe balance, and Treasury Bill automation. Max's trade-off is that you stay in FDIC-insured deposits at a lower platform fee, but the product is more about bank-account optimization than bill-aware checking autopilot.
The best product is the one that removes the constraint that actually caused the idle cash. If the constraint is bill timing, choose the checking-aware system. If the constraint is deposit coverage and rate allocation, choose the FDIC optimizer.
When Rivo Is the Right Fit
Choose Rivo if the cash you are evaluating is checking-adjacent cash.
The 30-day bill test comes first
That means the money is not supposed to be invested in equities, not needed immediately, and not best handled through a long-term portfolio. It is the amount above your safe balance that keeps surviving full payment cycles.
Rivo is not the product for every cash dollar. It is for the layer defined in Are You Keeping Too Much Money in Checking?: the extra cash that stays above bills, spending, autopay timing, and comfort buffer.
When MaxMyInterest Is the Right Fit
Choose MaxMyInterest if your priority is FDIC-insured bank-deposit optimization.
The FDIC-only requirement is a hard filter
That is a different buyer need. You may have more cash than one bank's standard coverage, prefer bank deposits over Treasury securities, want advisor visibility, or value a lower listed platform fee more than checking-specific automation.
Max may be the more logical option even if Rivo automation sounds appealing. If FDIC-only is a hard requirement, the answer should be Max or another FDIC-insured deposit solution, not a Treasury bill product.
Rivo vs MaxMyInterest Decision Tree
Use this decision tree before comparing rates.
A 7-question filter is enough for most buyers
The decision is simple only after the cash is labeled correctly. Checking cash, emergency cash, savings cash, tax cash, and investment cash should not all be forced into the same product.
Use this 10-point buyer-fit checklist as a quick tie-breaker. Add 1 point in the Rivo column or 1 point in the Max column for each row that describes your situation. A 7-3 or 8-2 split is usually more useful than a small headline-rate gap.
The checklist is not a rating, ranking, or return promise. It is a decision aid. If the score is 5-5, run a 30-day cash inventory and separate checking-surplus cash from savings cash before choosing.
Final Verdict: Rivo or MaxMyInterest?
Rivo is the better fit for people who want to keep their existing bank, define a safe checking balance, and automate the recurring movement of idle checking cash into short-duration U.S. Treasury Bills.
Rivo wins the checking-surplus workflow
MaxMyInterest is the better fit for people who want FDIC-insured deposit optimization across multiple bank accounts, especially for larger cash balances where coverage and account allocation matter more than checking-flow automation.
Max wins the FDIC-deposit workflow
Do not choose based on the highest number in a table. Choose based on the cash job, then validate the rate, fee, protection model, tax treatment, and access rules across at least 1 full bill cycle.
Pre-Decision Validation Checklist
Before choosing either product, validate the facts that change the decision. Rates, fees, transfer timing, and protection limits can change, so the right process is to check the current source before moving cash.
This checklist should be repeated if you publish or update the article after a rate change, fee change, or product update. A comparison that was accurate in July 2026 can become stale once rates, bank partners, or transfer policies change. For buyer decisions, check the rate source on day 1, day 30, and day 90 if the cash will stay idle for more than 3 months. Use 1 rate source, 1 fee source, 1 protection source, and 1 timing source before moving cash.
FAQ
Is Rivo the same kind of product as MaxMyInterest?
No. Rivo is automated cash management for idle checking cash and uses short-duration U.S. Treasury Bills through Jiko Securities. MaxMyInterest is deposit optimization across FDIC-insured bank accounts.
Is MaxMyInterest cheaper than Rivo?
On current public pricing, yes. Max lists 0.16% per year, subject to a $20 quarterly minimum, while Rivo charges 0.05% monthly, about 0.60% per year before compounding. The fee comparison should be paired with product-fit analysis because the products solve different workflows.
Does Rivo have FDIC insurance like MaxMyInterest?
No, not for Treasury bill holdings. FDIC deposit insurance covers eligible deposits at FDIC-insured banks, while Treasury bills are securities. Treasury investments are provided through Jiko Securities, Inc., a registered broker-dealer, member FINRA and SIPC.
Does MaxMyInterest use Treasury Bills?
MaxMyInterest's public individual-investor pages position the service around high-yield FDIC-insured bank accounts, not Treasury Bills. If you specifically want T-bill exposure, compare Rivo, TreasuryDirect, and brokerage T-bill options.
Which product is better for $20,000 in checking?
Rivo is usually the more relevant first comparison if the $20,000 is sitting in checking and part of it is above your safe balance. Max becomes more relevant if that $20,000 is savings cash and you want FDIC-insured deposit optimization rather than Treasury bill exposure.
Which product is better for $500,000 in cash?
MaxMyInterest is usually the more relevant first comparison if the main problem is FDIC coverage across banks. Rivo may still fit a specific checking-surplus layer, but it should not be treated as an FDIC-insured deposit replacement.
Related Rivo Reading
- To compare broader alternatives, read Rivo Alternatives.
- To compare Rivo with savings and T-bills, read Rivo vs High-Yield Savings vs Treasury Bills.
- To compare DIY T-bills with automation, read Rivo vs TreasuryDirect.
- To understand fees, read Rivo Fees Explained.
- To compare Rivo with a single FDIC-insured savings account, read Rivo vs Ally Bank Savings.
This guide covers the category split • How Much Money Should You Keep in Checking? • How Much Money Should You Keep in Checking? • Rivo vs High-Yield Savings vs Treasury Bills • What Is the Inertia Tax? • To see the product workflow, read How Does Rivo Autopilot Work?.

This article is educational and is not financial, investment, legal, accounting, or tax advice.
Yield rate reflects the 4-week T-bill rate when held to maturity. Rate does not include fees. Rates are subject to change. Minimum balance of $100 required to earn the stated rate.
Rivo is a fintech company, not a bank. Banking services provided by Jiko Bank, a division of Mid-Central National Bank. Jiko Group, Inc. and its affiliates do not provide legal, tax, or accounting advice. You should consult your legal and/or tax advisors before making any financial decisions. This material is not intended as a recommendation, offer or solicitation for the purchase or sale of any security or investment strategy. See FINRA BrokerCheck, Jiko U.S. Treasuries Risk Disclosures and Jiko Securities Inc. Form CRS.
Investments in T-bills: Not FDIC Insured - No Bank Guarantee - May Lose Value. All U.S. treasury investments and investment advisory services provided by Jiko Securities, Inc., a registered broker-dealer, member FINRA and SIPC. Securities in your account are protected up to $500,000. For details, please see www.sipc.org.
External References
- Rivo homepage
- Rivo product FAQ
- Rivo rate comparison table
- MaxMyInterest individual investors page
- MaxMyInterest FAQ
- Max Client Account Agreement
- FRED: National Rate, Interest Checking
- FDIC: Understanding Deposit Insurance
- TreasuryDirect: Treasury Bills
- TreasuryDirect: Tax Forms and Withholding
- SIPC: What SIPC Protects
- Jiko U.S. Treasuries Risk Disclosure

Ambrish Tyagi is the founder and CEO of Rivo. Previously led AI at Cruise and Amazon.
Follow on LinkedInGet Rivo Updates
Product news, money insights, and company updates.